The Vertical Umbrella Trap: Why "Biotech Accelerator" Doesn't Mean It Backs Your Subsector
A 'biotech' or 'climate' accelerator label is a marketing category, not proof it invests in your specific subsector. This post shows founders how to check a program's real portfolio pattern before spending a fall application slot on a mismatch.
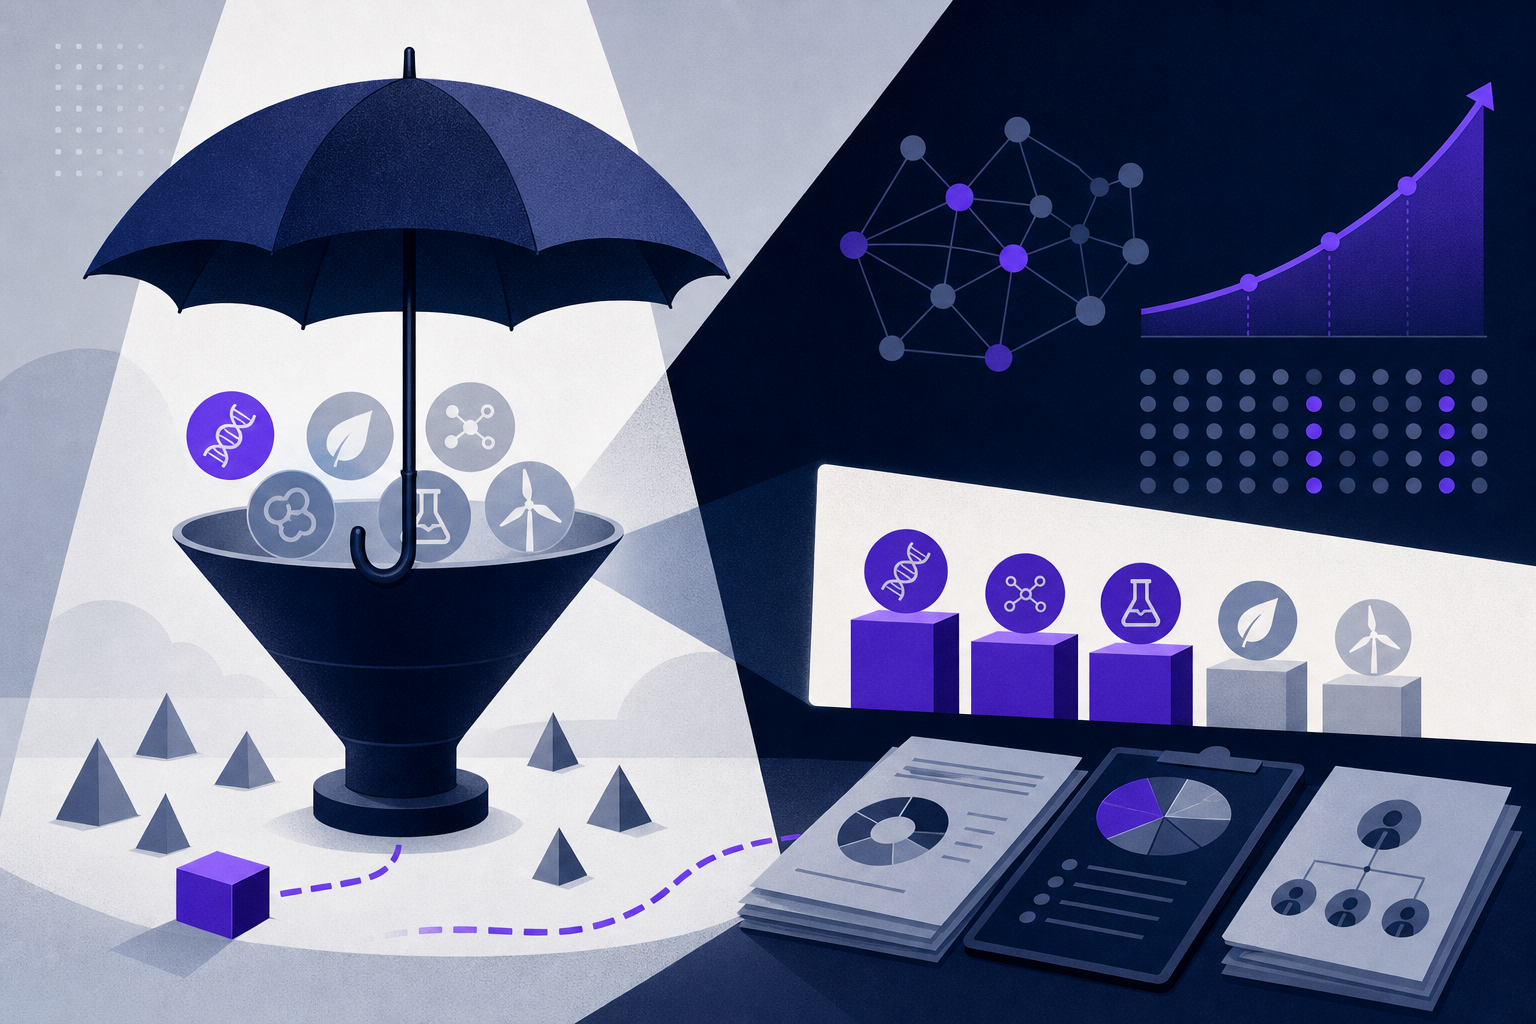
The label on the accelerator isn't the bet the accelerator is actually making
Here's the mismatch, stated plainly: a program marketing itself as a "biotech accelerator" funds a cohort that's 70% drug discovery and 10% diagnostics, with the rest scattered across tools and services. A program calling itself a "renewable energy accelerator" turns out to have backed almost exclusively grid storage and transmission companies, with maybe one solar company two cohorts ago. Both programs are telling the truth on their homepage. Biotech does include drug discovery and diagnostics. Renewable energy does include storage and generation. But "biotech" and "renewable energy" are umbrella terms covering subsectors that don't behave the same way, don't share the same investor networks, and don't get the same follow-on treatment. If you're a diagnostics founder who applies because the word "biotech" appeared in the program name, you may have just spent a fall deadline slot on a program built for someone else's business.
This isn't a knock on the programs. A biotech accelerator that leans hard into therapeutics isn't lying, it's specializing, probably because its partners have deep pharma relationships and that's where they can genuinely help. The problem is on the founder's side: treating the umbrella label as a filter, when it's really just a category tag.
Why this matters more than the check size on the term sheet
Founders comparing accelerators tend to start with the numbers: check size, equity percentage, whether the SAFE has an MFN clause. Those matter, and we've written about how the bigger check can be the worse deal and what MFN and pro-rata actually mean for your Series A. But none of that data is useful if the program's real specialty doesn't match your subsector.
Here's why: a big part of an accelerator's value is what happens after demo day, when its network of follow-on investors decides whether to write the next check. That follow-on pattern isn't random. It clusters around whatever the partners actually understand and have relationships in. A renewable energy program whose alumni track record is stacked with grid storage companies has investor relationships built around grid storage, not around solar manufacturing or EV charging infrastructure. If your startup is in a different renewable energy subsector, you're applying to a program whose most valuable asset (its network) doesn't actually point at you. The check size on paper is the same. The value behind it isn't.
How to check this yourself before you apply
You don't need inside information to catch this. You need to look at the right thing, which is the portfolio, not the pitch.
Pull the actual company list, not the tagline
Go to the accelerator's site and find its list of portfolio companies, usually organized by cohort. Ignore the mission statement at the top of the page. Read the company names and one-line descriptions instead. This is the same discipline we recommend for fintech: check the portfolio's actual go-to-market pattern rather than trusting the word "fintech" to mean anything specific.
Sort by subsector, not by vertical
Group the last two or three cohorts by what the companies actually do. For biotech, that might mean separating therapeutics, diagnostics, medtech devices, and research tools into their own buckets. For climate, separate grid storage from carbon capture from ag-tech from EV infrastructure. Whichever bucket has the most companies is the accelerator's real specialty, regardless of what the umbrella term implies.
Compare that pattern to your own subsector
If your subsector isn't represented in the last few cohorts at all, that's not automatically disqualifying. Programs do expand. But it's a signal to ask harder questions before you apply, not after: does this program have partners with subsector-specific experience, or would you be the test case for a category the accelerator hasn't actually funded yet?
We go deeper on this exact check in how to tell if a vertical-specific accelerator actually stayed in its vertical, which walks through reading portfolio composition as its own diagnostic step, separate from reading the terms.
Where Accelerator Atlas fits into this check
This is the part where founders usually give up, not because the check is conceptually hard, but because doing it manually across a dozen programs before a fall deadline is a research project on its own. That's the gap the directory closes. Each of the 105 programs listed in Accelerator Atlas is filterable by vertical, and 102 of them are verified against the accelerator's own primary documents, not scraped summaries. Every program shows its source and its check-date, so instead of trusting a program's self-description of its vertical, you can see where the data came from and confirm it yourself.
That's not the same as us telling you which subsector a program favors. We don't manufacture confidence we don't have: if the data isn't solid, the program is flagged Secondary or Unverified rather than getting a guess dressed up as fact. But it does mean you're starting from a verified list instead of a pile of marketing pages, which cuts real time out of the portfolio check above.
Do this before the fall wave closes, not after
The fall application wave is the second major deadline season of the year, and if you're a biotech or climate founder still deciding where to apply, you likely have more than one deadline coming up in the next few weeks. That's exactly the moment this check matters most, because the cost of skipping it isn't abstract. An application takes hours to prepare well. A slot in a cohort, if you get in, costs equity. Spending either on a program whose real specialty is adjacent to yours, not aligned with it, is a cost you can avoid with an afternoon of portfolio reading.
If you're juggling more than one vertical deadline this season, tracking accelerator application deadlines by vertical is worth pairing with this check, so you're not doing subsector research the same week an application is due.
Search before you submit
Browse the Accelerator Atlas directory to compare biotech and climate programs side by side, filter by vertical and check size, and see the source behind every listing before you commit an application to this fall's deadline wave.
Frequently asked
How do I know what subsector an accelerator actually invests in?
Skip the tagline and pull the portfolio list. Look at the last two or three cohorts, sort companies by what they actually build (not the accelerator's category label), and see where the cluster sits. If a 'biotech' program's list is 80% therapeutics and 20% diagnostics, that tells you more than any mission statement.
Is a climate accelerator the same as a cleantech accelerator?
Not necessarily. Both terms get used loosely, and a program calling itself either can lean hard into one subsector (grid storage, carbon capture, ag-tech) while barely touching others. Treat 'climate' and 'cleantech' as umbrella marketing terms, then verify the actual subsector mix in the portfolio before you assume fit.
Why does subsector match matter more than check size when picking an accelerator?
A program's follow-on funding pattern is only predictive if it tracks your specific subsector. A diagnostics startup raising in a program whose follow-on investors mostly write checks into drug discovery isn't getting the network effect the check size implies, no matter how attractive the number looks on paper.
New posts in your inbox
One digest a week. Deadline alerts only for verticals you pick. Unsubscribe anytime.